How big are daily candle bodies and wicks in the major currency pairs?
- Markets
- Period
- –
- Period length
- 2005 – 2026
- Data
- 1-hour candles built from one-minute data
- Sample
- 39,471 market-days from 7 markets (about 5,640.0 trading days each)
- Source
- OANDA CFD one-minute mid prices · New York trading days
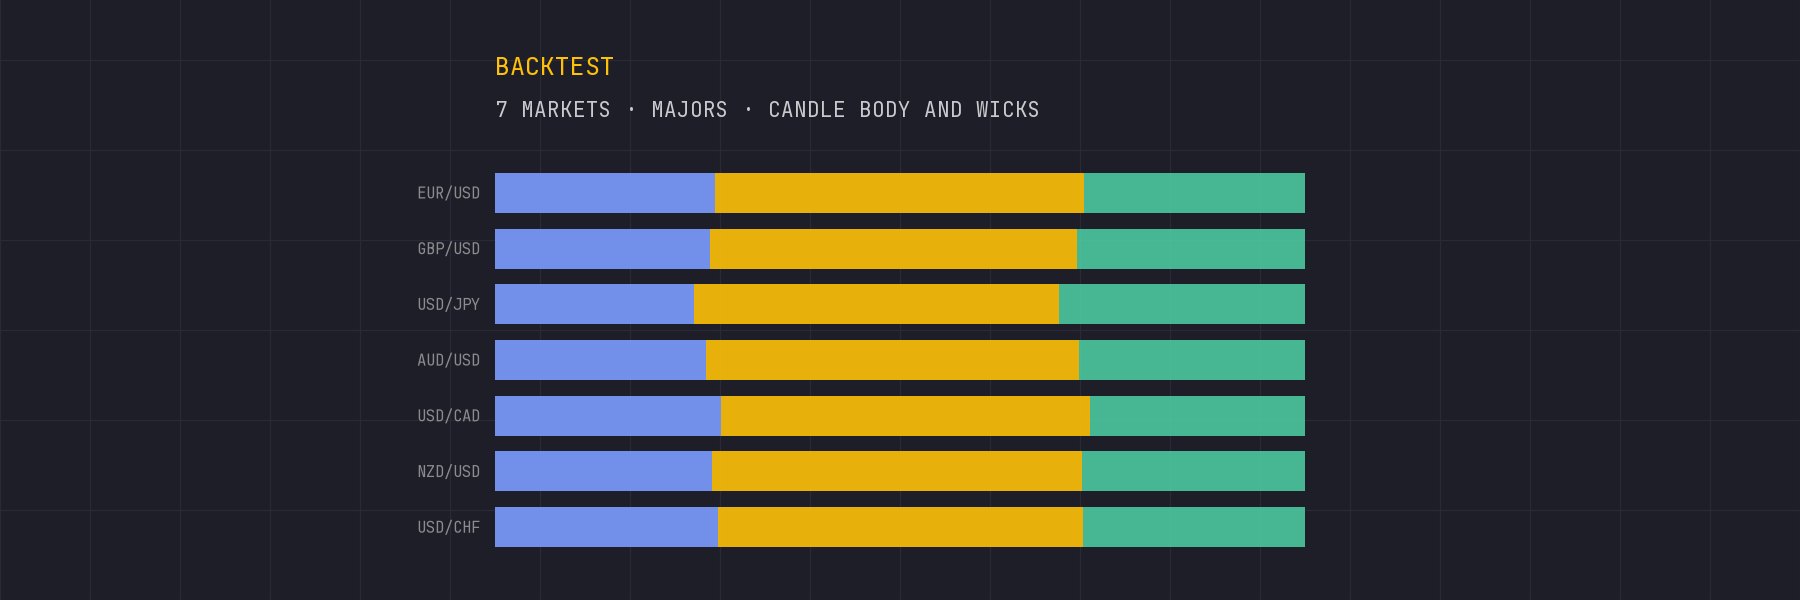
A daily candle is a body, from the open to the close, and two wicks: the prices the day reached but did not close at. We measured how much of each day's range was body and how much was wick, and how often the body was so small that the candle is a doji, for 7 markets from 2005 to September 30, 2026: EUR/USD, GBP/USD, USD/JPY, AUD/USD, USD/CAD, NZD/USD and USD/CHF.
The daily candle used here
The usual forex convention ends the trading day at 17:00 New York time, and every market on this page is cut the same way: a day runs from 17:00 to 17:00 New York time, Monday to Friday. The open is the open of the day's first 1-hour candle, the close is the close of its last one, and the high and the low are the highest and lowest prices of the whole day. Charts that cut the day at midnight UTC draw different daily candles, so their counts will differ.
Candle body and wicks: Majors together
On an average day, the body covered 45.5% of the day's range, the upper wick 26.7% and the lower wick 27.9%. The lower wick was the longer one, by 1.2 points.
10.0% of days were a doji: a body no bigger than 10% of the day's range.
Market by market
The biggest average body was AUD/USD at 46.0%, the smallest USD/CHF at 45.0%. Doji days were most common in USD/JPY (10.6%) and least common in USD/CAD (9.6%).
Year by year
Over the 21 full years in which all 7 markets traded, the group's share of doji days ranged from 8.9% (2017) to 11.2% (2019). The results section below shows every market by year.
What this is useful for
The wicks are the part of the day's travel that did not hold until the close. Knowing how big they usually are puts a single day's candle in context. It says nothing about direction.
Results by market
All years together, one row per market; the last row adds the markets together. Every value is a percentage of the days counted. Pick a market's name to see it year by year.
Majors
7 markets
| Market | Days | Share of range | Doji | ||
|---|---|---|---|---|---|
| Upper wick | Body | Lower wick | |||
| EUR/USD | 5638 | 27.2 | 45.6 | 27.3 | 9.9 |
| GBP/USD | 5639 | 26.5 | 45.4 | 28.1 | 9.7 |
| USD/JPY | 5639 | 24.5 | 45.1 | 30.3 | 10.6 |
| AUD/USD | 5639 | 26.1 | 46.0 | 27.9 | 9.6 |
| USD/CAD | 5639 | 27.9 | 45.5 | 26.6 | 9.6 |
| NZD/USD | 5638 | 26.8 | 45.6 | 27.5 | 10.2 |
| USD/CHF | 5639 | 27.6 | 45.0 | 27.4 | 10.3 |
| All majors | 39471 | 26.7 | 45.5 | 27.9 | 10.0 |
Year by year
USD/CHF: 5639 complete trading days, 2005-01-03 to 2026-09-30.
- Upper wick
- Body
- Lower wick
- Bars, top to bottom: average share of the day's range; doji: body at most 10% of the day's range.
| Year | Days | Share of range | Doji | Chart | ||
|---|---|---|---|---|---|---|
| Upper wick | Body | Lower wick | ||||
| 2005 | 260 | 28.7 | 45.2 | 26.1 | 10.4 | |
| 2006 | 259 | 27.9 | 44.4 | 27.7 | 11.6 | |
| 2007 | 259 | 27.1 | 43.7 | 29.3 | 11.6 | |
| 2008 | 260 | 25.9 | 45.4 | 28.7 | 11.2 | |
| 2009 | 259 | 32.1 | 42.1 | 25.7 | 12.0 | |
| 2010 | 260 | 27.9 | 46.3 | 25.8 | 7.3 | |
| 2011 | 260 | 28.3 | 45.3 | 26.4 | 10.4 | |
| 2012 | 259 | 30.5 | 43.5 | 26.0 | 11.6 | |
| 2013 | 259 | 30.2 | 43.7 | 26.1 | 11.2 | |
| 2014 | 259 | 27.2 | 46.1 | 26.7 | 8.1 | |
| 2015 | 259 | 24.8 | 46.8 | 28.4 | 9.3 | |
| 2016 | 259 | 28.1 | 41.7 | 30.2 | 14.3 | |
| 2017 | 258 | 27.6 | 45.2 | 27.2 | 7.4 | |
| 2018 | 259 | 26.9 | 43.7 | 29.4 | 13.5 | |
| 2019 | 259 | 27.1 | 44.6 | 28.3 | 12.0 | |
| 2020 | 260 | 26.8 | 45.3 | 27.9 | 8.5 | |
| 2021 | 260 | 29.5 | 46.0 | 24.6 | 10.8 | |
| 2022 | 259 | 26.2 | 46.2 | 27.5 | 12.0 | |
| 2023 | 259 | 25.6 | 44.7 | 29.7 | 8.9 | |
| 2024 | 260 | 27.2 | 46.4 | 26.4 | 8.5 | |
| 2025 | 259 | 25.3 | 47.0 | 27.8 | 8.9 | |
| 2026* | 194 | 25.4 | 47.0 | 27.6 | 7.7 | |
| All years | 5639 | 27.6 | 45.0 | 27.4 | 10.3 | |
Every value is a percentage of the days counted. * 2026 runs until 2026-09-30.
How this was measured
- Data: OANDA CFD one-minute mid prices (halfway between bid and ask). They are grouped into 1-hour candles in New York time, so US daylight saving time is followed automatically, including the older rules before 2007.
- Trading day: 17:00 to 17:00 New York time, Monday to Friday. Asia 17:00–02:00, London 02:00–08:00, New York 08:00–17:00.
- Which days count: a day needs at least one traded hour in every session and at least 75% of the usual number of trading hours for that market in that year. Holidays and half days drop out this way.
- Which years count: a market's year is used only if it has at least 100 complete days. Years where a market did not trade in all three sessions are therefore left out for that market.
- Ties: when two sessions reach exactly the same price, the earlier session gets it.
- Totals: "together" simply adds up the market-days of the 7 markets. Markets in the same group move together (the crosses share currencies, the US indices move as one), so 39,471 market-days are not 39,471 independent observations.
- Year by year in the text: only full calendar years in which every one of the 7 markets has data are used, so the group is the same in every year. The current, unfinished year is not part of that range (it is in the tables, marked with *).
- Period: 2005 (or the first year with full data for a market) to September 30, 2026.
- Daily candle: open of the first 1-hour candle, close of the last one, high and low of the whole day (17:00 to 17:00 New York time).
- Body and wicks: body = |close − open|, upper wick = high − the higher of open and close, lower wick = the lower of open and close − low, each divided by the day's range and averaged over all days with a range above zero. The three add up to 100%.
- Doji: a body no bigger than 10% of the day's range.
Historical statistics for research and education, not trading advice. Past market behaviour does not guarantee future results.